

Fixed-rate, variable-rate, or hybrid mortgage: which one is right for you, with real-life examples
We explain the differences between each type of mortgage, along with their pros and cons, to help you choose the best option for you.
When choosing a mortgage, there is no "perfect" option for everyone; the choice will depend on your personal situation, your income, your job stability, your risk tolerance, and your medium- and long-term plans.
From aFinance, as experts in mortgage intermediation, we explain clearly how each type of mortgage works and what you can expect from them so that you can make an informed decision tailored to your real needs. In addition, we will show you practical examples and real comparisons that will help you visualize how much you would pay in each case.
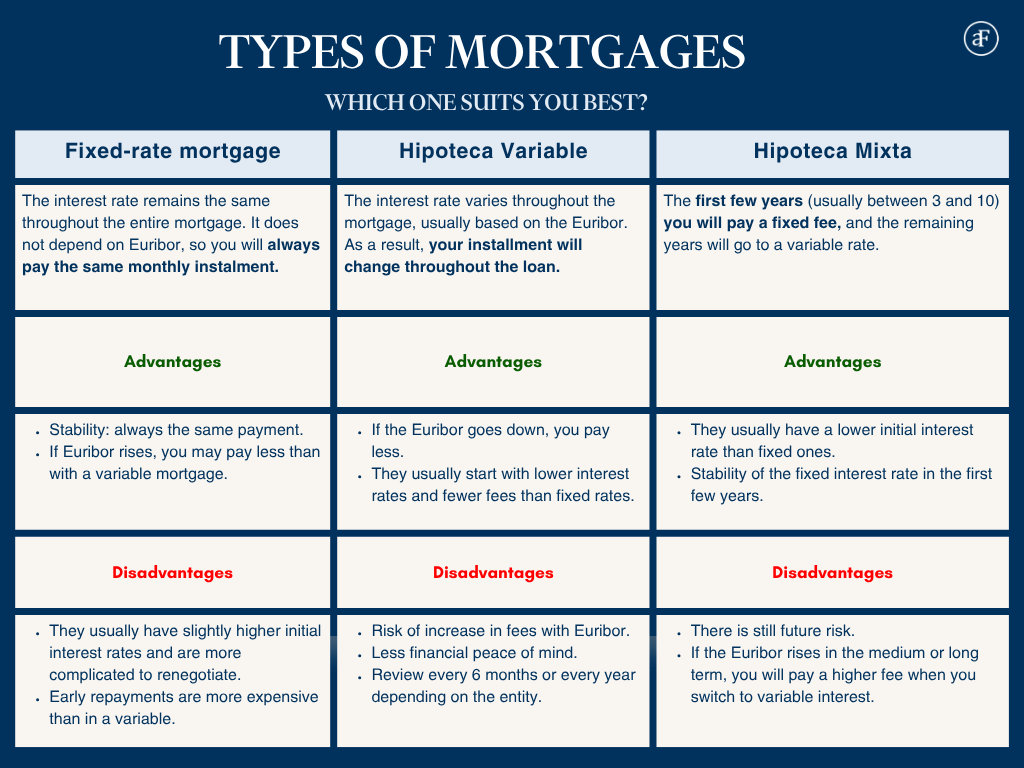
Fixed-rate mortgage
Thanks to this stability, a fixed-rate mortgage offers you great peace of mind, allowing you to plan your long-term family budget without fear of unexpected increases. It is especially interesting in times of economic uncertainty or when the Euribor is high or showing an upward trend..
Although its initial interest rate is usually somewhat higher than that of variable-rate mortgages, many of our clients prefer to assume a slightly higher cost in exchange for avoiding risks and gaining financial foresight.
In short, the fixed-rate mortgage is your ideal option if you are looking for security and stability in your long-term investment.
Do you want to know the best fixed interest rate for your profile?
CONSULT YOUR FIXED MONTHLY INSTALLMENT
Variable-rate mortgage
Normally, reviews are carried out every 6 or 12 months, at which time the bank recalculates the installment by applying the new value of the Euribor plus the differential agreed upon at signing. This type of mortgage usually starts with a lower initial interest rate than a fixed-rate mortgage, making it an attractive option for those looking to pay less in the first few years or who trust that the Euribor will remain stable or even drop. However, it implies a higher risk, since if the Euribor goes up, your monthly installment will also increase.
Therefore, the variable-rate mortgage is suitable for you if you can handle market fluctuations and if interest rates tend to fall in the medium or long term.
How would a rise or fall in the Euribor affect your installment?
REQUEST YOUR FREE PRE-STUDY HERE
Mixed-rate mortgage
The initial stage usually lasts between 3 and 10 years, depending on the conditions of each bank. From that moment on, your installment will become variable, being able to go up or down at each review, generally every 6 or 12 months.
This type of mortgage is ideal if you want stability at the beginning and flexibility afterwards, especially if you believe your income will increase over time or if you expect interest rates to fall in the future.
If you want to compare how your mixed mortgage installment would look compared to a fixed or variable one, at aFinance we calculate it for you without obligation:
REQUEST YOUR MORTGAGE INSTALLMENTS
What type of mortgage suits you best according to your profile?
Each type of mortgage has advantages depending on your needs and your risk tolerance. Below, we present three real examples of clients we have helped choose the most appropriate option according to their profiles:
✔️ Alejandra and Miguel were looking for stability without risks.
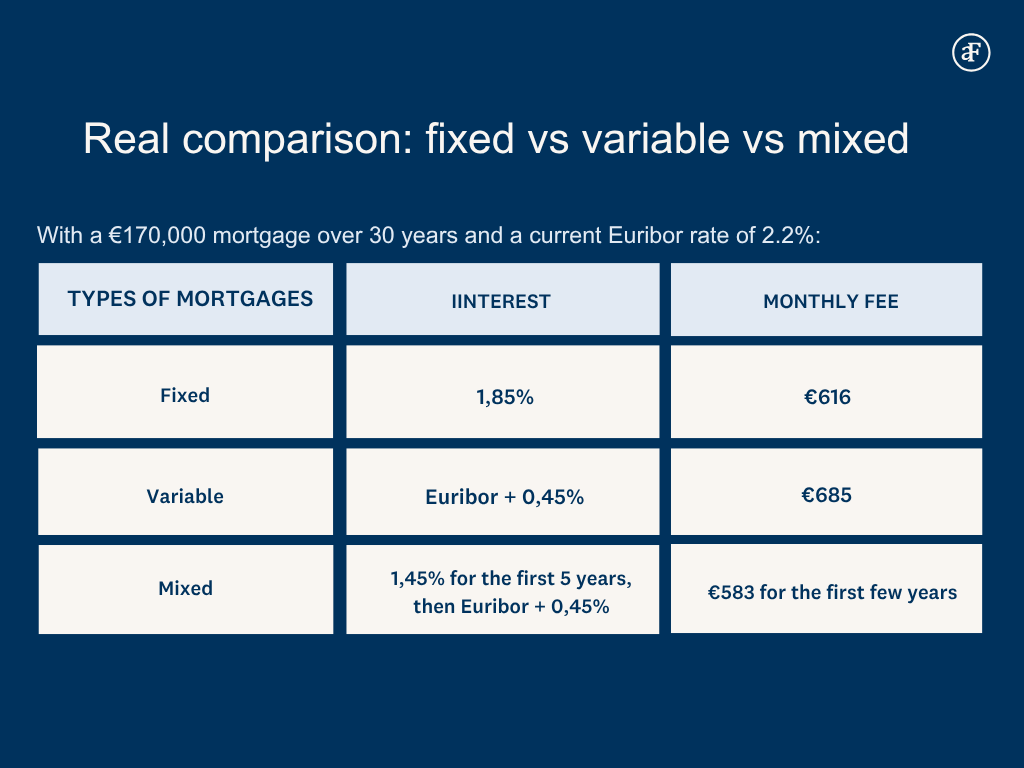
They got their fixed-rate mortgage at 1.85% for 30 years
EThis couple had a tight budget. From aFinance, we compared and negotiated with several banking institutions, obtaining the most competitive interest rate on the market, offering them total stability and avoiding unexpected increases in their payments.
✔️ María and Marc had financial leeway.
Variable-rate mortgage at 0.45%
With the capacity to handle periods of higher payments, we secured for this couple from Barcelona the variable-rate mortgage that best suited their profile and their needs.
✔️ Laura was buying a home alone in Valencia.
100% financing on a mixed-rate mortgage at 1.9% for 8 years and then Euribor + 0.45%
Laura wanted to pay less during the first few years, as she knew her income would increase over time. After having worked abroad, we at aFinance helped her get the most appropriate mortgage with 100% financing.
How much will I pay depending on my mortgage type?
Choosing the mortgage type that best suits you depends not only on your needs and profile, but also on how it will affect your monthly payments. Below, we present a comparative example showing how much you could pay depending on the chosen mortgage type:
At aFinance we analyze your profile, negotiate with banking institutions, and obtain offers that are not normally available to the individual client, improving interest rates, commissions, and terms.
Start now and discover how much you would pay for your mortgage
REQUEST YOUR FREE PRE-STUDY HERE
- Featured news
-
 Best mortgages in Spain 2026: These are the best mortgages for each monthSeptember 30th 2026
-
 70% of civil servants who use aFinance secure a 100% mortgage, whether for a primary or secondary reAugust 5th 2026
-
 100% financing mortgage: how to buy a home without savingsJuly 2nd 2026
-
 Your mortgage in less than a month: this is how aFinance's Express Mortgage worksMay 6th 2026
-
 aFinance strengthens its growth in Barcelona with the addition of Sandra Bautista as office directorApril 21st 2026
-
 Mortgage for young people in 2026: how to buy your first home without savingsMarch 30th 2026